How a Connecticut Liquor Distributor Stopped the Annual Premium Climb with a Captive
Author
Article Summary
A Connecticut liquor distributor joined the OneDigital PRO Captive to address rising health insurance costs, keeping underlying costs per employee essentially flat while maintaining benefits and freeing funds to reinvest in employees.
A Connecticut distributor with fewer than 100 employees moved from a fully insured plan to the OneDigital PRO Captive and kept costs flat. Here's how they did it.
The Situation: Fully Insured Plan Costs Increasing Beyond the Budget
For a growing business, few line items are as frustrating as the health plan renewal. A liquor distributor in Connecticut with fewer than 100 employees knew the feeling well. Their fully insured plan with a local Health Maintenance Organization (HMO) was climbing by at least 5% every year, and they had no visibility into the medical or pharmacy claims driving those increases. Without data, they had no leverage to push back.
The cost of that cycle went beyond the budget spreadsheet. Rising plan costs were limiting the company's ability to raise employee wages, which in turn weighed on business performance and growth. Every renewal meant the same tradeoff: absorb the increase or shift more cost to the people they were trying to take care of.
If that sounds familiar, you're not alone. Many mid-sized employers are asking whether there's a better way to fund their health plan, and for this company, the answer was a move to self-funding through a captive.
The Solution: Transparency, Flexibility and Control
In 2018, the distributor moved from a fully insured plan to a self-insured plan within the OneDigital PRO Captive. A group captive lets smaller and mid-sized employers self-fund their benefits while sharing risk with other members, so a single large claim doesn't carry the same weight it would for a standalone employer. If you're new to the model, our Moneyball Benefits Podcast episode on captive solutions is a good starting point.
The change gave the company a very different relationship with its health plan. Here's what the transition included:
- An independent third-party administrator (TPA) and a carved-out pharmacy benefit manager (PBM), both with transparent pricing and contractual provisions
- Specialty drug management programs to address one of the fastest-growing areas of plan spend
- A member navigation and advocacy platform to help employees find the right care and get more from their benefits
- Robust communication campaigns that educated employees on the value of their plan, which increased understanding of and participation in it
Our Self-Funded Center of Excellence supports employers through exactly this kind of transition, from feasibility to implementation.
The Results: Claims Down, Benefits Intact
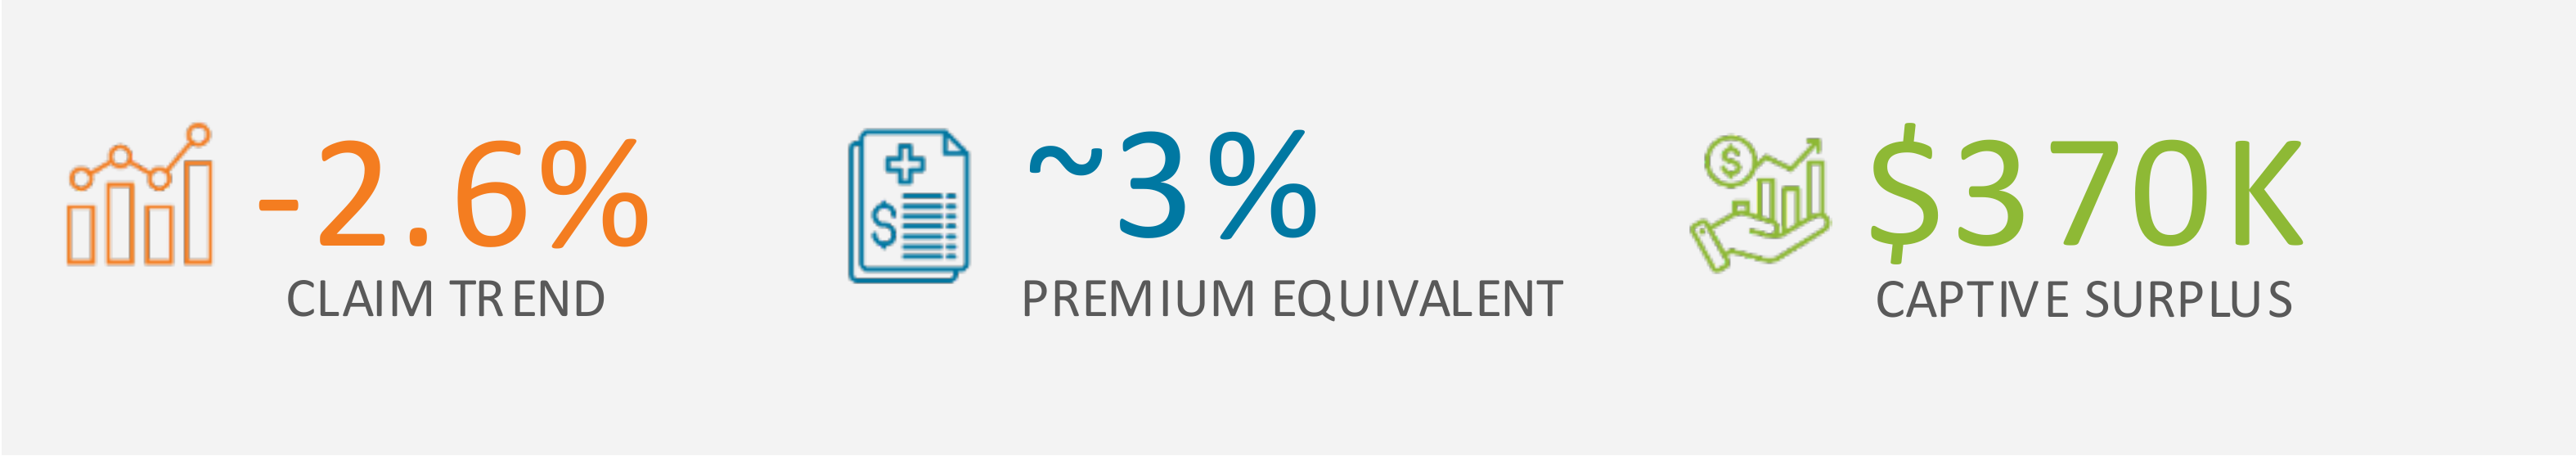
Since joining the captive in 2018, the group has seen a negative 2.6% claim trend, approximately 3% premium equivalent, and $370,000 captive surplus:
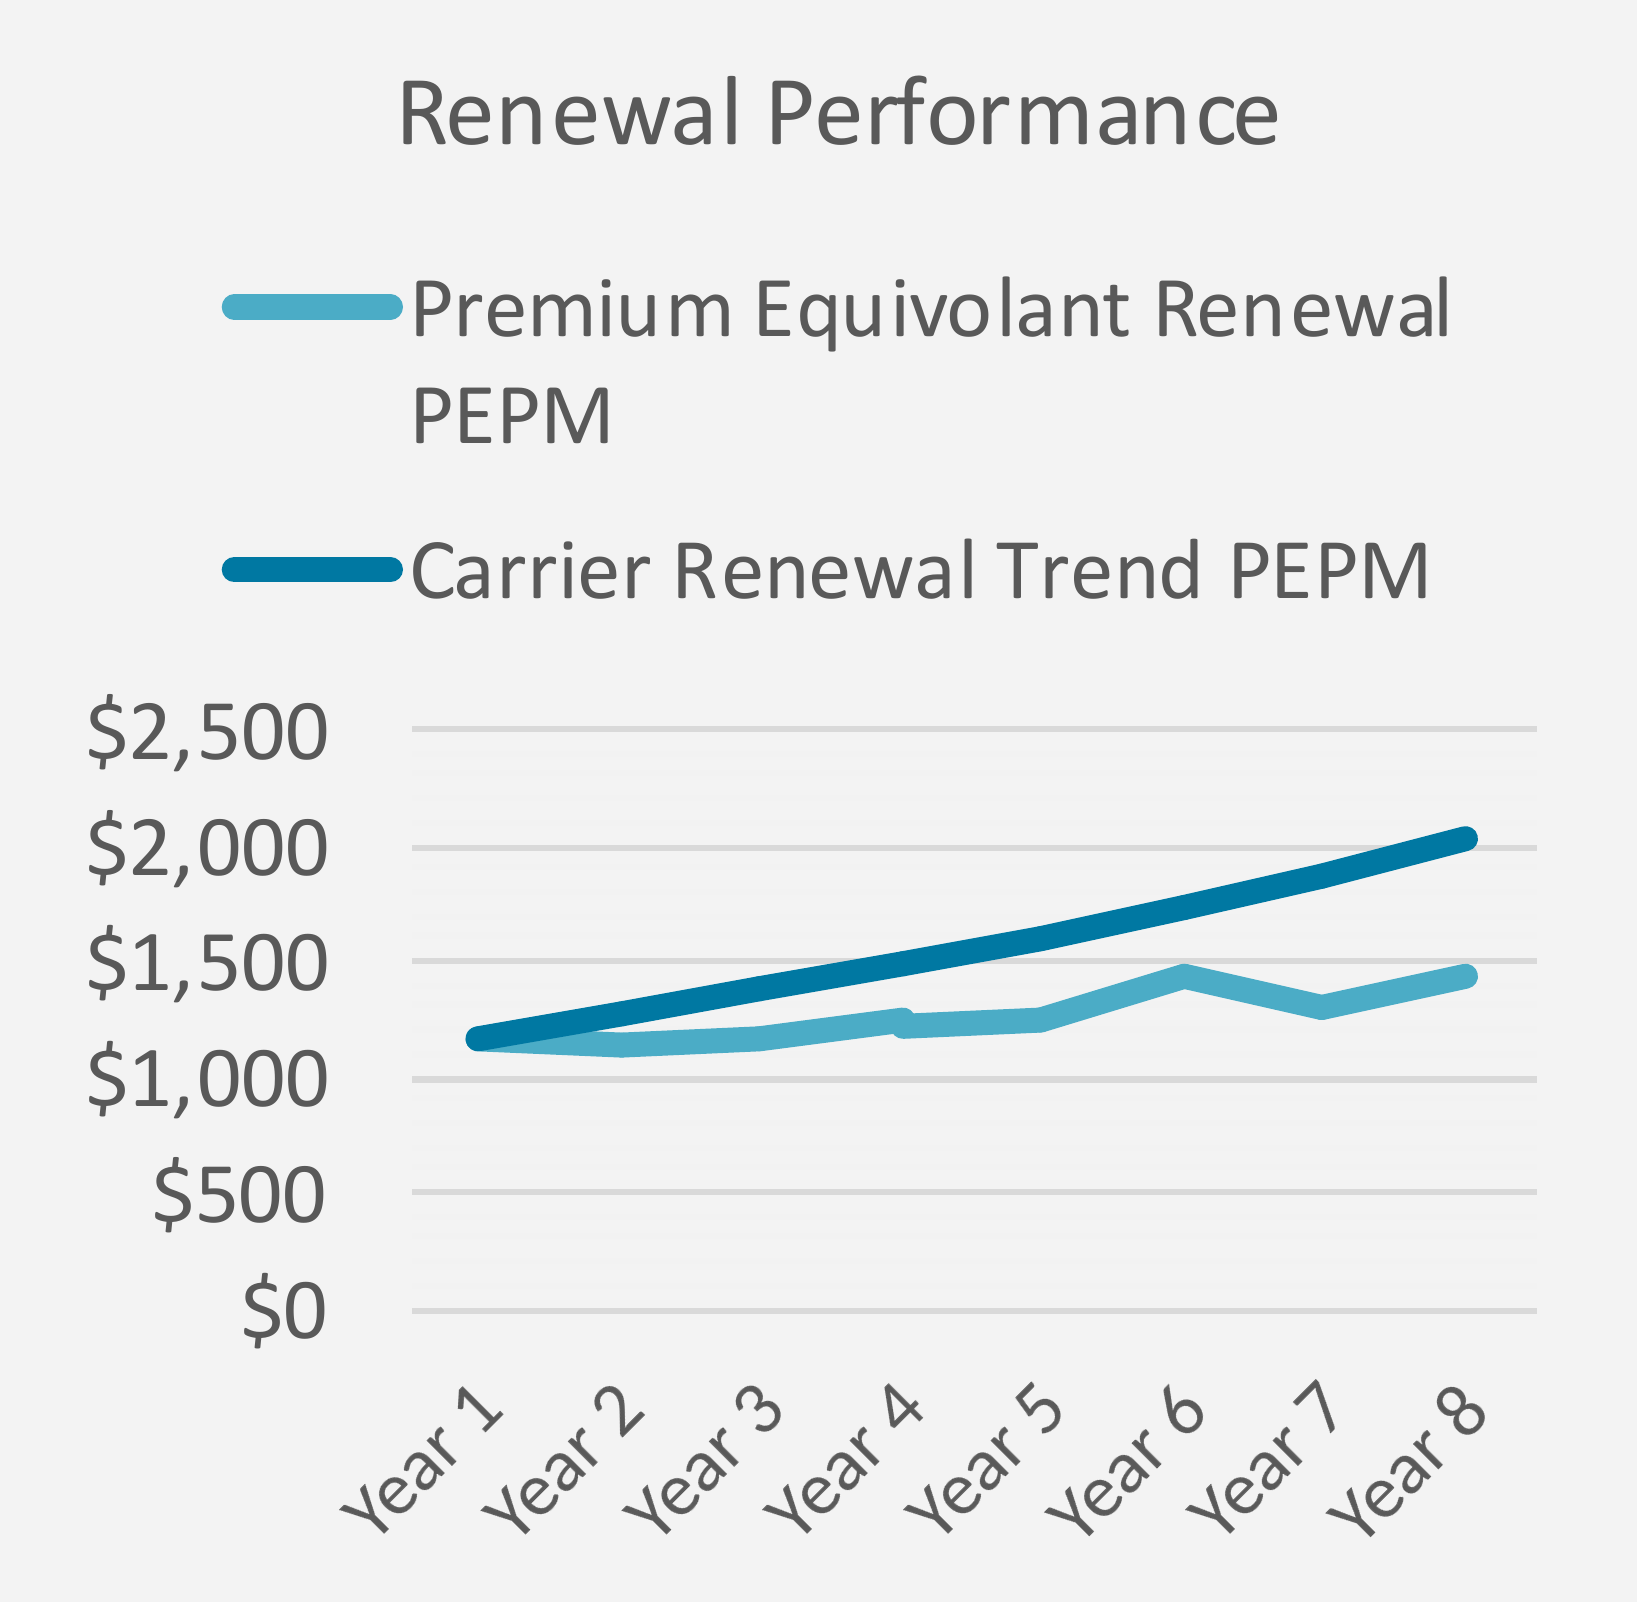
Renewal Performance:
Claims Performance:
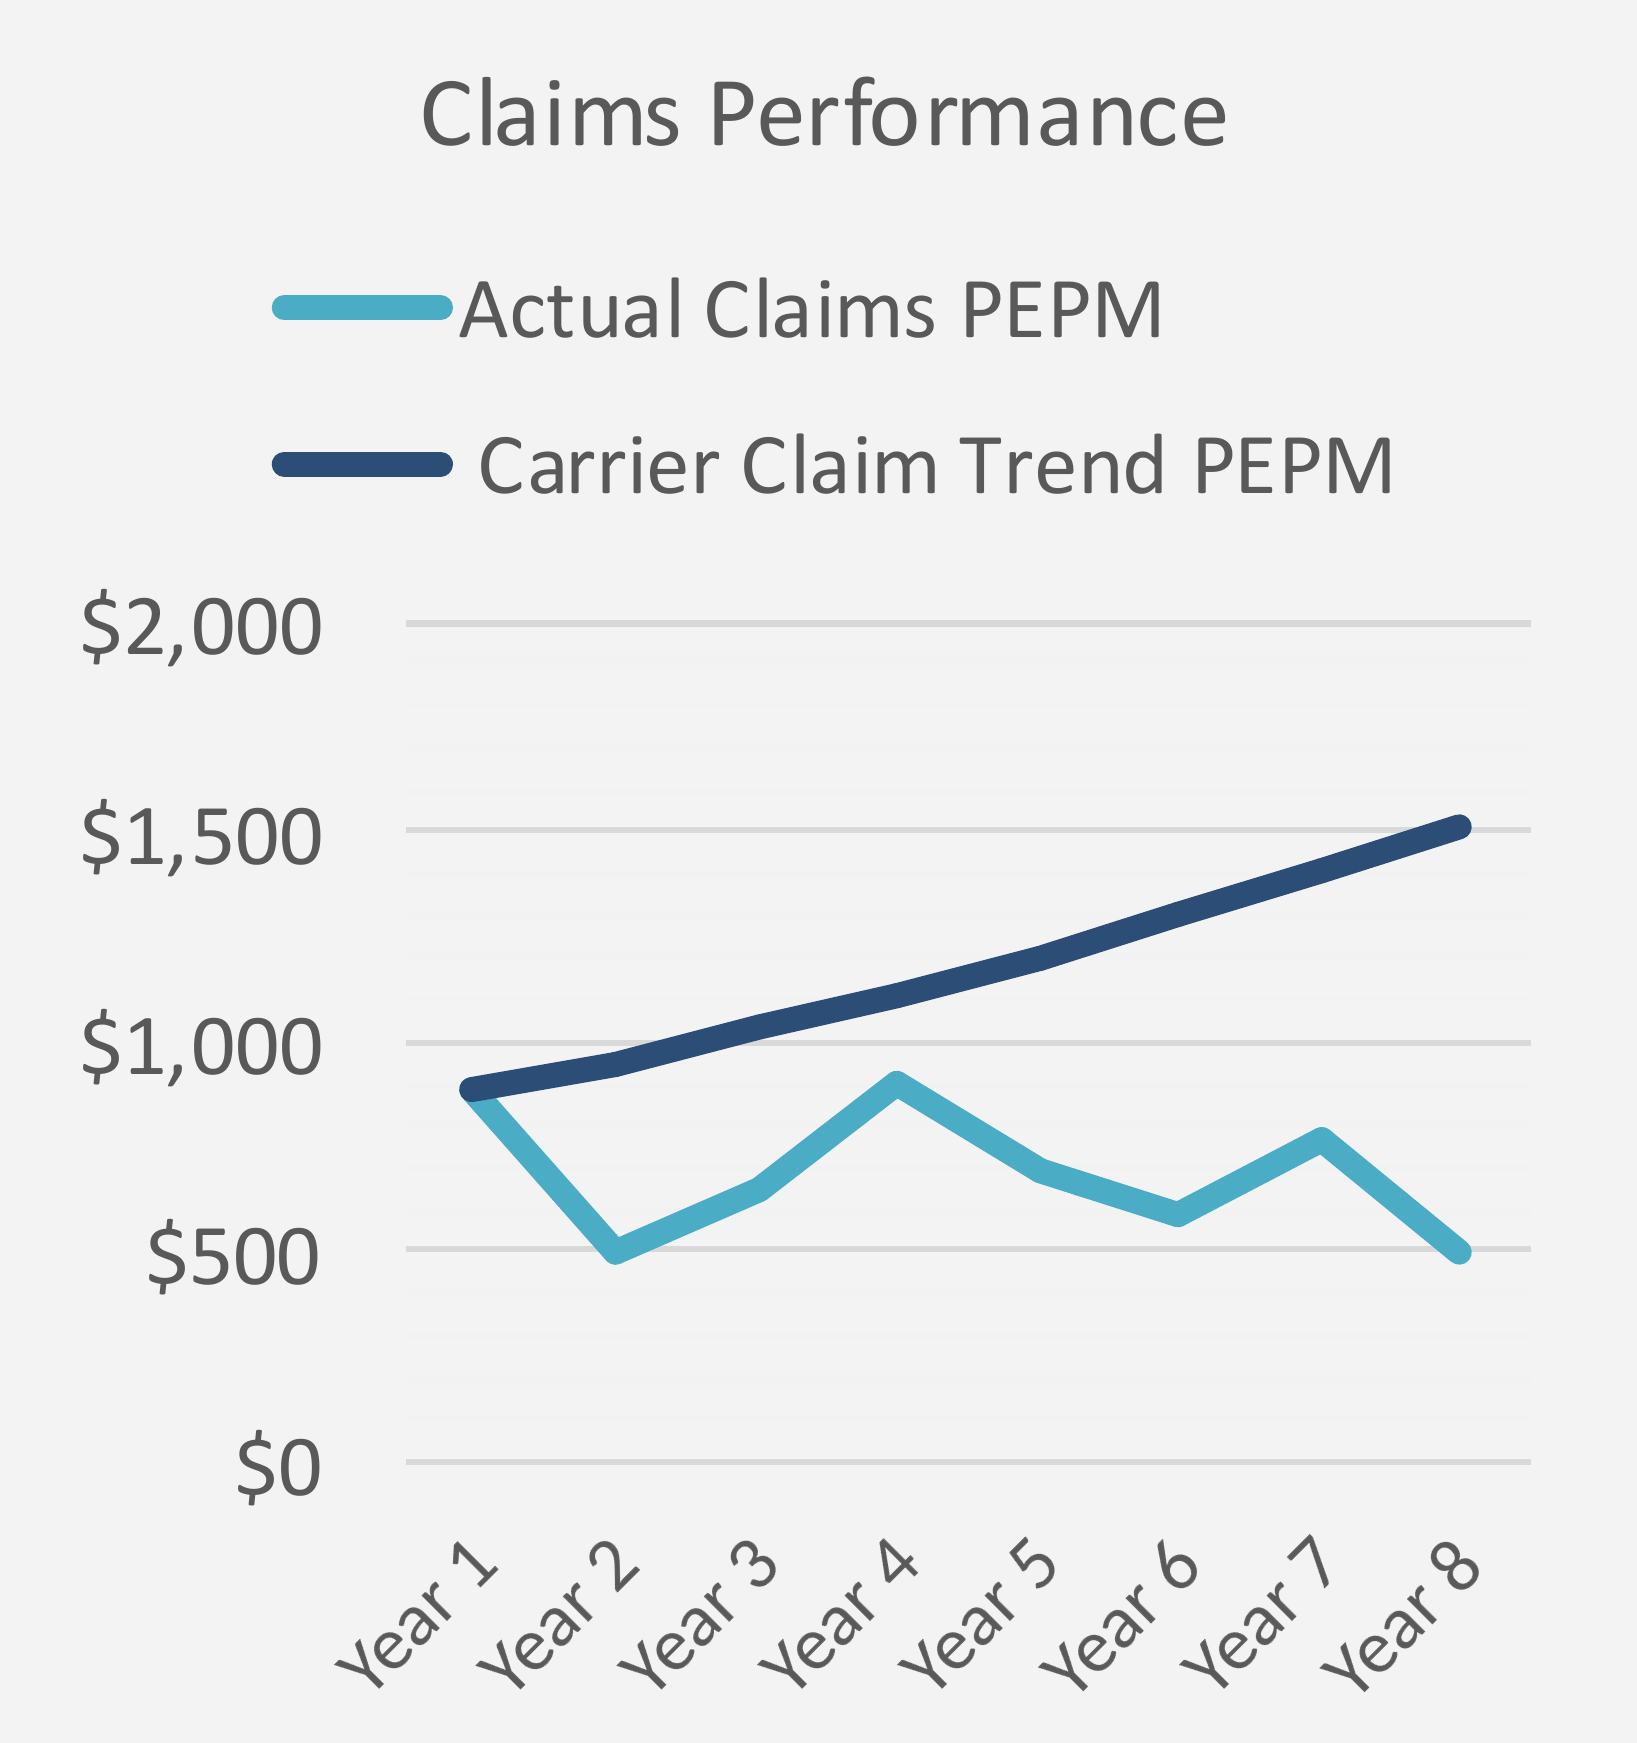
The charts tell the story. While the projected carrier trend kept climbing year after year, the group's actual claims and premium equivalent stayed well below it.
Just as important, those savings didn't come from cutting benefits. The company has maintained the same level of benefits and employee contributions with minimal to no changes. They've even been able to reinvest in their employees' health savings accounts (HSAs), which helped the company navigate and end a labor strike.
With transparent data, leadership could finally make informed, strategic decisions about the direction of their health plan, rather than reacting to whatever number arrived at renewal.
"Prior to joining the OneDigital Captive, our health insurance costs were increasing at a minimum of 5% per year. we had no insight into our medical and pharmacy claims and had to leverage to control our costs. With the captive, our underlying costs have remained essentially flat (on a per capital basis)."
— President, Connecticut Liquor Distributor
Is a Captive Right for Your Organization?
Every employer's situation is different, and a captive isn't the right fit for everyone. But if you're facing recurring premium increases, limited access to your claims data, or pressure on wages and growth because of benefits costs, it's worth a look. OneDigital's captive programs have also drawn industry recognition, including honors at the 2025 Berkley Symposium.
Ready to explore your options? Learn more about OneDigital Captive Solutions, download the full case study, or connect with a OneDigital advisor to see whether self-funding could work for you.
Captive FAQs
What is a group captive for health insurance? A group captive is an arrangement in which multiple employers self-fund their health benefits and pool risk together, typically with stop loss coverage. It gives smaller and mid-sized employers access to the transparency and control of self-funding with more protection against large claims.
Can a small employer self-fund its health plan? Yes. In this case study, a company with fewer than 100 employees moved from a fully insured plan to a self-insured plan within the OneDigital PRO Captive in 2018.
Does moving to a captive mean cutting benefits? Not in this case. The company maintained the same level of benefits and employee contributions with minimal to no changes.
What changes when you leave a fully insured plan? Employers typically gain access to their claims data, an independent TPA, a carved-out PBM with transparent pricing, and the ability to add programs such as specialty drug management and member advocacy.
For more information on OneDigital’s captive solution, visit: OneDigital's Captive Solutions.
About OneDigital
OneDigital’s team of fierce advocates helps businesses and individuals achieve their aspirations of health, success and financial security. Our insurance, financial services and HR platform provides personalized, tech-enabled solutions for a contemporary work-life experience. Nationally recognized for our culture of caring, OneDigital’s teams enable employers and individuals to do their best work and live their best lives. More than 100,000 employers and millions of individuals rely on our teams for counsel and access to fully integrated worksite products and services and the retirement and wealth management advice provided through OneDigital Investment Advisors. Founded in 2000 and headquartered in Atlanta, OneDigital maintains offices in most major markets across the nation. For more information, visit onedigital.com.
Disclaimer: This case study is illustrative in nature and highlights the savings of a specific client under particular circumstances unique to them. Your experiences may vary depending on your business needs, operating conditions, market conditions and other variables. This is not a guarantee or prediction of future performance or savings for any client. Consult with our team to review how our services might apply to your unique situation.